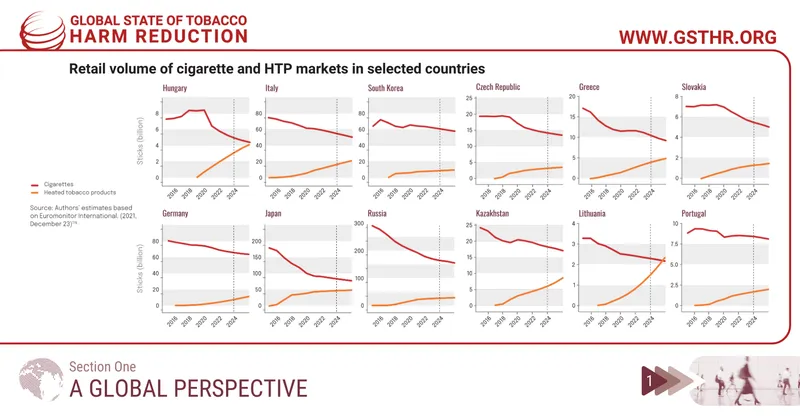
Retail volume of cigarette and HTP markets in selected countries
Heated tobacco product (HTP) sales have seen significant growth since 2016, in Asia Pacific and Western and Eastern Europe. In many countries, this has coincided with a drop …

In Czech Republic, smoking is legal but there some restrictions and regulations around tobacco. Under these regulations, the sale and use of cigarettes are legal. Purchasing them online and from vending machines is permitted. Also, importing cigarettes for trade is allowed with an appropriate license. However, health warnings on cigarette packaging are required, the minimum legal age for purchasing tobacco products is 18 years, and there are legal restrictions on smoking in public places. A total taxation rate of 75.63% including an excise tax rate of 28.27% are applied on cigarettes.
Statistics show that in 2024 the Czech Republic had around 2.4 million current adult smokers, corresponding to an adult current smoking prevalence of 26.3%. This indicates a slight reduction from 2022 when the current smoking prevalence was 27.5%. Among adult males, the current smoking prevalence was 30.8%, while among adult females it was 21.9% in 2024. The adult daily smoking prevalence was 18.2% in 2023. Mortality data show that in 2021 tobacco smoking led to 15,764 deaths in the country, including 11,007 among males and 4,757 among females. Overall, smoking accounted for 11.37% of all deaths in the Czech Republic in 2021, including 15.1% of male deaths and 7.24% of female deaths.
| Year | Value | Reference/Comment |
|---|---|---|
| 2019 | 2.8 million | 1A |
| 2024 | 2.4 million | 1B |
| Year | Value | Reference/Comment |
|---|---|---|
| 2013 | 29.9% | 1A A |
| 2014 | 31.4% | 1A A |
| 2015 | 24.1% | 1A A |
| 2016 | 28.6% | 1A A |
| 2017 | 25.2% | 1A A |
| 2018 | 28.5% | 1A A |
| 2019 | 31.5% | 1B |
| 2019 | 24.9% | 1A A |
| 2020 | 23.1% | 1A A |
| 2020 | 28.3% | 1C |
| 2021 | 24.4% | 1A A |
| 2022 | 27.5% | 1D B |
| 2022 | 24.4% | 1A A |
| 2023 | 23% | 1E C |
| 2023 | 24.6% | 1A A |
| 2024 | 22.4% | 1A A |
| 2024 | 26.3% | 1F |
| Year | Value | Reference/Comment |
|---|---|---|
| 2019 | 27.3% | 1A |
| 2020 | 23.5% | 1B |
| 2022 | 23.3% | 1C A |
| 2024 | 21.9% | 1D |
| Year | Value | Reference/Comment |
|---|---|---|
| 2019 | 35.6% | 1A |
| 2020 | 33.4% | 1B |
| 2022 | 31.7% | 1C A |
| 2024 | 30.8% | 1D |
| Year | Value | Reference/Comment |
|---|---|---|
| 2017 or earlier | 25% | 3A A |
| 2002 | 24.1% | 3B |
| 2003 | 27.2% | 3B |
| 2004 | 25.4% | 3B |
| 2005 | 24.3% | 3B |
| 2006 | 23.4% | 3B |
| 2007 | 24% | 3B |
| 2008 | 21.8% | 3B |
| 2009 | 23.8% | 3B |
| 2010 | 22.8% | 3B |
| 2011 | 21.7% | 3B |
| 2012 | 22.9% | 3B |
| 2013 | 22.2% | 3B |
| 2014 | 22.3% | 3B |
| 2015 | 18.2% | 3B |
| 2016 | 19.6% | 3B |
| 2017 | 18.4% | 3B |
| 2018 | 21.1% | 3B |
| 2019 | 18.1% | 3B |
| 2020 | 16.6% | 3B |
| 2021 | 17.6% | 3B |
| 2022 | 16.2% | 3B |
| 2023 | 15.9% | 3B |
| 2023 | 18.2% | 3C B |
| 2024 | 16.4% | 3B |
| Year | Value | Reference/Comment |
|---|---|---|
| 2017 or earlier | 17% | 3A A |
| 2002 | 18.1% | 3B |
| 2003 | 22.6% | 3B |
| 2004 | 20.1% | 3B |
| 2005 | 19.4% | 3B |
| 2006 | 19.5% | 3B |
| 2007 | 18.8% | 3B |
| 2008 | 18.8% | 3B |
| 2009 | 18% | 3B |
| 2010 | 16.5% | 3B |
| 2011 | 18.8% | 3B |
| 2012 | 19.6% | 3B |
| 2013 | 17.4% | 3B |
| 2014 | 18.5% | 3B |
| 2015 | 14.8% | 3B |
| 2016 | 15.6% | 3B |
| 2017 | 14.5% | 3B |
| 2018 | 17.9% | 3B |
| 2019 | 15.2% | 3B |
| 2020 | 12.2% | 3B |
| 2021 | 13.3% | 3B |
| 2022 | 12% | 3B |
| 2023 | 11.9% | 3B |
| 2024 | 14.4% | 3B |
| Year | Value | Reference/Comment |
|---|---|---|
| 2017 or earlier | 33% | 3A A |
| 2002 | 30.9% | 3B |
| 2003 | 32.2% | 3B |
| 2004 | 31.1% | 3B |
| 2005 | 29.8% | 3B |
| 2006 | 27.7% | 3B |
| 2007 | 29.6% | 3B |
| 2008 | 24.9% | 3B |
| 2009 | 29.7% | 3B |
| 2010 | 29.3% | 3B |
| 2011 | 24.7% | 3B |
| 2012 | 26.3% | 3B |
| 2013 | 27.2% | 3B |
| 2014 | 26.4% | 3B |
| 2015 | 21.8% | 3B |
| 2016 | 23.8% | 3B |
| 2017 | 22.6% | 3B |
| 2018 | 24.5% | 3B |
| 2019 | 21.1% | 3B |
| 2020 | 21.2% | 3B |
| 2021 | 22% | 3B |
| 2022 | 20.6% | 3B |
| 2023 | 20.1% | 3B |
| 2024 | 18.6% | 3B |
| Year | Value | Reference/Comment |
|---|---|---|
| 2016 | 17,664 | 1A |
| 2021 | 15,764 | 1B A |
| Year | Value | Reference/Comment |
|---|---|---|
| 2016 | 6,114 | 1A |
| 2021 | 4,757 | 1B A |
| Year | Value | Reference/Comment |
|---|---|---|
| 2016 | 11,550 | 1A |
| 2021 | 11,007 | 1B A |
| Year | Value | Reference/Comment |
|---|---|---|
| 2016 | 17.84% | 1A |
| 2021 | 11.37% | 1B A |
| Year | Value | Reference/Comment |
|---|---|---|
| 2016 | 11.3% | 1A |
| 2021 | 7.24% | 1B A |
| Year | Value | Reference/Comment |
|---|---|---|
| 2016 | 21.3% | 1A |
| 2021 | 15.1% | 1B A |
Heated tobacco product (HTP) sales have seen significant growth since 2016, in Asia Pacific and Western and Eastern Europe. In many countries, this has coincided with a drop …
The TPD is a Directive of the EU which means that all EU countries must ‘transpose’ or incorporate the TPD requirements into their national laws. The only flexibility …
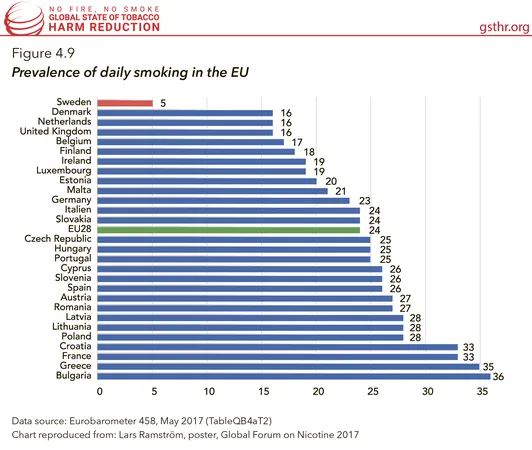
Sweden now has the lowest level of smoking among men than for any other country in Europe. According to the European Commission’s Eurobarometer 2017 report, only five percent …